

Cash Advance - No credit Check
4.7

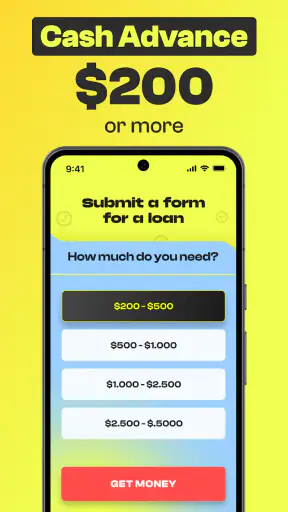
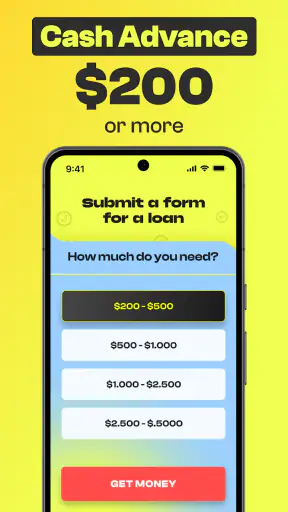
When money is tight, the hardest part can be figuring out what to do before a bill comes due. Cash Advance - No Credit Check is a finance app from D.J. Advance App built around that short-term gap: it aims to help people explore a cash advance without relying on a traditional credit check. I’d treat it as one possible tool for a temporary cash-flow problem, not as extra income or a substitute for a budget. The important question is not only whether you can request money, but whether the repayment fits your next pay cycle.
When the connection becomes part of the process
A cash-advance app is most useful when you can complete its steps at the moment you need to make a decision. In this case, that may mean having a stable internet connection while setting up an account, reviewing any available terms, and handling the financial details involved in an application. I wouldn’t wait until I was standing at a checkout or rushing between appointments to begin. A calm moment gives you room to read carefully instead of tapping through because a payment feels urgent.
Connectivity matters for another reason: a financial decision can involve several separate screens and pieces of information. If your connection drops halfway through, you may be unsure whether a step went through or whether you need to try again. My practical advice is to use a reliable connection, allow time to finish, and check the app’s current status before repeating an action. That small pause can prevent confusion and helps you avoid acting on an assumption.
Using it around real-life errands
The mobile format makes the app relevant to ordinary situations: reviewing a possible advance at home, checking details during a break, or considering whether a short-term expense can wait until payday. Still, I would separate browsing from committing. If you open the app while distracted, use that visit to understand the options; make the borrowing decision later, when you can focus on repayment dates and your other bills.
Imagine a necessary household expense arrives a few days before payday. Before turning to an advance, I’d write down the amount due, the date it must be paid, and the money already committed to rent, utilities, food, and transport. Then I’d compare that shortfall with the repayment that would follow. If repaying the advance would leave the same essentials uncovered next week, the app has not solved the problem; it has moved it. If the expense is genuinely urgent and the next pay cycle can absorb repayment, exploring an offer may be more reasonable.
What to do when a step stalls
Unexpected delays are especially frustrating in finance apps because the user may be dealing with a deadline. If a screen stops responding or a request appears incomplete, I’d first check the connection and reopen the app rather than submitting the same information repeatedly. Then I’d look for an on-screen status or instructions before deciding what to do next. This is a careful workflow, not a guarantee that a stalled request will recover in a particular way.
I’d also avoid treating an initial screen or estimate as final approval. An app can help you explore an option, but eligibility and the terms offered are what matter when deciding whether to proceed. Take a moment to confirm what you are agreeing to, what repayment is expected, and when it is due. If anything is unclear, pausing is better than accepting a commitment just to get through the process faster.
Keeping mobile data and financial attention in check
For data-conscious use, I’d open the app when I have a dependable connection rather than repeatedly refreshing it while travelling or relying on a weak signal. More important than saving mobile data is protecting your attention: avoid reviewing an offer while multitasking, and don’t leave account or repayment details for a rushed moment. Financial information deserves the same care you would give it on any other service.
Before linking financial information or continuing through an application, read the explanations and permissions presented in the app itself. I wouldn’t assume that “no credit check” means no review of any kind, or that every person will receive the same result. It’s sensible to understand what information is requested and why before sharing it. That makes the decision more deliberate and helps distinguish a useful option from one you are not comfortable using.
Getting Started with Ease
First off, downloading the app was a breeze. Available on both Android and iOS, you can find it easily on your app store of choice. Once I had it installed, setting up an account was straightforward. The interface is clean and user-friendly, making it super easy to navigate even if you’re not tech-savvy. Just a few taps and I was ready to explore what this app had to offer.
How It Works
The concept behind Cash Advance - No Credit Check is pretty simple. You get access to small loans without the need for a credit check. This is a game-changer for anyone who’s been turned down by traditional lenders because of their credit score. The app essentially connects you with lenders who are willing to overlook your credit score and focus on other factors like your bank account activity.
Once you’ve linked your bank account, the app analyzes your income and spending patterns to determine your eligibility. Don’t worry, it’s all secure, and they only access the necessary data to make a decision. I found this feature particularly reassuring because privacy is always a concern when dealing with financial apps.
Features That Stand Out
One of the coolest features of this app is the speed. I mean, who wants to wait days for approval when you need cash ASAP? With this app, once you’re approved, the funds can be in your account as fast as the next business day. It’s like having a fast-forward button for your finances!
Another aspect that impressed me was the transparency. The app lays out all the fees and terms clearly, so there are no hidden surprises. You can easily see how much you’ll need to pay back and when, which helps in planning your repayment strategy.
And let’s talk about flexibility. If you’re worried about high interest rates, the app offers competitive rates and flexible repayment options. You can choose a repayment plan that suits your financial situation, which is a lifesaver if you’re juggling multiple expenses.
Who Can Benefit?
Now, you might be wondering if this app is for you. Honestly, if you’re someone who needs quick cash without the hassle of a credit check, this app could be a great fit. Whether it’s an unexpected bill or an urgent purchase, having access to a cash advance can be a huge relief.
It’s also ideal for those who are working on building or repairing their credit score. Since the app doesn’t rely on traditional credit checks, it won’t impact your credit score negatively. This way, you can handle emergencies without the added stress of affecting your credit history.
Choosing between an advance and other options
Compared with a credit card, a cash advance app is aimed at a short-term cash gap rather than ongoing purchases. A card may be more practical if you can pay the balance responsibly and want a familiar way to cover an expense; the app may be worth considering when a credit check is a concern and the specific offer works for your situation. Neither choice is automatically cheaper, so I’d compare the full repayment obligation rather than judging by how quickly money might arrive.
It is also worth comparing the app with asking a bill provider about a payment arrangement, using savings, or getting help from someone you trust. Those options may avoid taking on a new repayment, though they will not suit every situation. I’d use an advance only after checking whether the expense can be delayed or handled another way, and only if the repayment date does not collide with essentials. Convenience is useful, but it should not be the only reason to borrow.
Who should pause before applying
This app is not the right fit for someone who needs a long-term solution to a recurring shortfall. If each pay period is already fully committed, another repayment can make the following week tighter and prompt a cycle of borrowing. In that situation, I’d prioritize reviewing regular expenses, contacting creditors about due dates, or seeking local financial guidance rather than using a short-term advance to cover a structural gap.
I’d also skip an application if you are not comfortable sharing the financial information requested, cannot confidently identify the repayment date, or are unsure how the total obligation fits your budget. A no-credit-check approach does not remove the need to assess affordability. The app’s appeal is access and convenience; the trade-off is that you still have to make a careful decision about the consequences.
Small habits that make the experience more useful
One practical tip is to prepare before opening the application: know the exact shortfall, your next expected income date, and the bills that will be due before then. That gives you a realistic ceiling instead of encouraging you to treat any available amount as money to spend. I’d also keep a written note of the repayment commitment alongside the bill it is meant to cover, so the advance stays connected to a specific need rather than blending into everyday spending.
Another useful habit is to review the offer when you are not under immediate pressure. Read the amount, timing, and repayment terms together, not as separate details, and compare them with your calendar. A quick calculation can reveal whether the repayment falls during a week with other large expenses. If it does, the advance may be technically available but practically unmanageable.
How it fits among finance apps
Cash advance tools occupy a narrower role than a full budgeting app or bank account: they focus on bridging a short-term gap, while budgeting tools help plan ahead and a bank account supports day-to-day money management. This app should not be expected to replace either. I’d use it, if at all, as a specific option to evaluate for a one-off need, while keeping a separate view of regular income and spending.
The app is free to download, and its Everyone age rating makes it broadly accessible, but neither point tells you whether a particular advance is affordable or suitable. It has a 4.7 average from around 18,000 ratings, with over 500,000 installs, which suggests many people have tried it; popularity is still not a substitute for checking your own terms. D.J. Advance App’s finance offering is currently version 1.1.3 and supports Android 7.0 and up. I’d check that your device is compatible and that the app is current before beginning a time-sensitive process.
My connectivity verdict
For me, the mobile convenience is most valuable when I can sit down, connect reliably, and review the decision without rushing. It is less helpful as a last-second fix if a weak connection, a busy setting, or pressure to act keeps me from checking the details. Use it deliberately, confirm the status of any step before repeating it, and keep a backup plan for an urgent bill rather than assuming an app process will resolve everything on demand.
Final Thoughts
After using Cash Advance - No Credit Check, I can see why it’s gaining popularity among users looking for financial flexibility. It’s efficient, user-friendly, and most importantly, it keeps things simple. No one wants to jump through hoops when they’re already stressed about finances, right?
Overall, I’d say this app is worth checking out if you’re in need of a quick financial solution. Just remember to borrow responsibly and make sure you can handle the repayments to avoid any potential pitfalls. If you’re interested in giving it a try, you can download it directly from your app store and see how it works for you!
4.7
2.27K Reviews
Pros
- Quick and easy cash access.
- No credit check required.
- User-friendly interface.
- Fast approval process.
- Secure transactions.
Cons
- High interest rates.
- Limited cash amount.
- Requires stable income.
- Not available in all states.
- Potential for debt cycle.


